A reconciliation is finished when every difference has an owner, its evidence and a decision from someone with the authority to make it. How to reconcile a supplier statement against accounts payable, two worked examples, why the balances disagree, and who may approve each fix when an accounting firm does the work for its clients.
AI Answer Summary
Vendor statement reconciliation, also called supplier statement reconciliation, compares a supplier's statement of account with your accounts payable records to find and resolve differences in invoices, payments, credits and balances.
The process matches the two sides line by line, classifies every difference, gathers the evidence each one needs, and resolves it through someone with the authority to record, apply, dispute or pay. A statement records what the supplier believes is owed, and any payment still goes through the normal approval route.
When an accounting firm reconciles for a client it also audits or reviews, the AICPA's independence rules make recording, approving and paying the client's decisions. The firm can investigate and propose a resolution, the client decides, and the reconciliation records who decided what.
What Is Vendor Statement Reconciliation?
Vendor statement reconciliation is the comparison of a supplier's statement of account with your accounts payable records, to find and resolve every difference between what the supplier believes you owe and what your books say you owe.
The term varies by region and by firm. "Supplier statement reconciliation" is more common in the UK and in many outsourced bookkeeping teams, and some practitioners say "vendor reconciliation." They describe the same control.
Its value comes from where the statement comes from. Every other record in accounts payable is created inside the business: the invoice entered, the payment released, the credit applied. A supplier statement is the one regular document produced entirely outside it, by someone keeping their own ledger of the same relationship. When the two ledgers disagree, one of them is missing something, and the statement is often the first place a problem becomes visible:
- An invoice that never reached AP, sitting unpaid and accruing late fees or putting the account on hold
- A payment the supplier received but applied to the wrong invoice, or has not recorded at all
- A credit note the supplier issued that nobody on your side has used
- An invoice recorded twice in AP, which a payment run will eventually pay twice
This article is written for accounting firms reconciling suppliers on behalf of their clients, where the questions of who may decide what become as important as the matching itself. The step-by-step process, the examples and the resolution matrix apply equally to an in-house AP team reconciling its own suppliers.
Vendor Statement Reconciliation Compared With Bank, Three-Way and AP Reconciliation
Four reconciliations in accounts payable and cash are easy to confuse, and each answers a different question from a different pair of records.
| Process | Records compared | Main question |
|---|---|---|
| Bank reconciliation | Bank statement and the cash ledger | Does recorded cash activity agree with the bank? |
| Vendor statement reconciliation | Supplier statement and AP records | Does the supplier agree with what is owed and what has been settled? |
| Three-way matching | Purchase order, receiving record and invoice | Does this invoice agree with what was ordered and received? |
| AP subledger reconciliation | AP subledger and the general ledger control account | Does the detail in AP agree with the ledger? |
The differences matter in practice. Three-way matching works one invoice at a time, before it is paid, and can only check invoices that reached AP, so an invoice that never arrived stays invisible to it. Bank reconciliation confirms cash moved but says nothing about which invoice a payment settled in the supplier's books. AP subledger reconciliation proves the detail adds up to the ledger, which is no help if the detail itself is incomplete.
Vendor statement reconciliation is the only one of the four that brings in the counterparty's view of the whole account, which is why it catches what the others miss: invoices never received, payments misapplied, and credits forgotten. Our guides to automating bank reconciliation and three-way matching in accounts payable cover those two processes in depth.
What a Supplier Statement Contains, and What It Proves
A supplier statement summarizes the supplier's view of the account for a period, and as evidence it is stronger than your own records and weaker than a confirmation sent directly to an auditor.
Most statements contain:
- The account name and number, and the period or statement date
- An opening balance carried from the previous statement
- Invoices issued in the period, with numbers, dates and amounts
- Payments received, sometimes with the remittance reference
- Credit notes and adjustments
- A closing balance, often with an aging of what remains unpaid
Formats vary widely. Some suppliers send a clean PDF each month, others send a spreadsheet export, an emailed table or a portal download, and a few send nothing unless asked. Statements often omit purchase order numbers, use the supplier's own invoice numbering, and show dates as the supplier booked them rather than when you received the invoice.
Its evidential weight is worth understanding, especially for firms that also audit. Under the PCAOB's audit evidence standard, AS 1105, paragraph .08, evidence from a knowledgeable source independent of the company is generally more reliable than evidence from internal sources, and evidence obtained directly by the auditor is more reliable than evidence obtained indirectly. A supplier statement is independent of the client's books, but when it reaches the auditor through the client it has passed through the client's hands. A confirmation the supplier sends straight to the auditor is stronger. For public company audits, the standard's paragraph .10A adds that when the company provides external information in electronic form, such as a statement forwarded as a PDF, the auditor has to understand where it came from and whether it was changed along the way.
That is why statements turn up so often in audits, both as items on the PBC list and as evidence in the search for unrecorded liabilities that our guide to audit workpapers works through.
How to Reconcile Vendor Statements, Step by Step
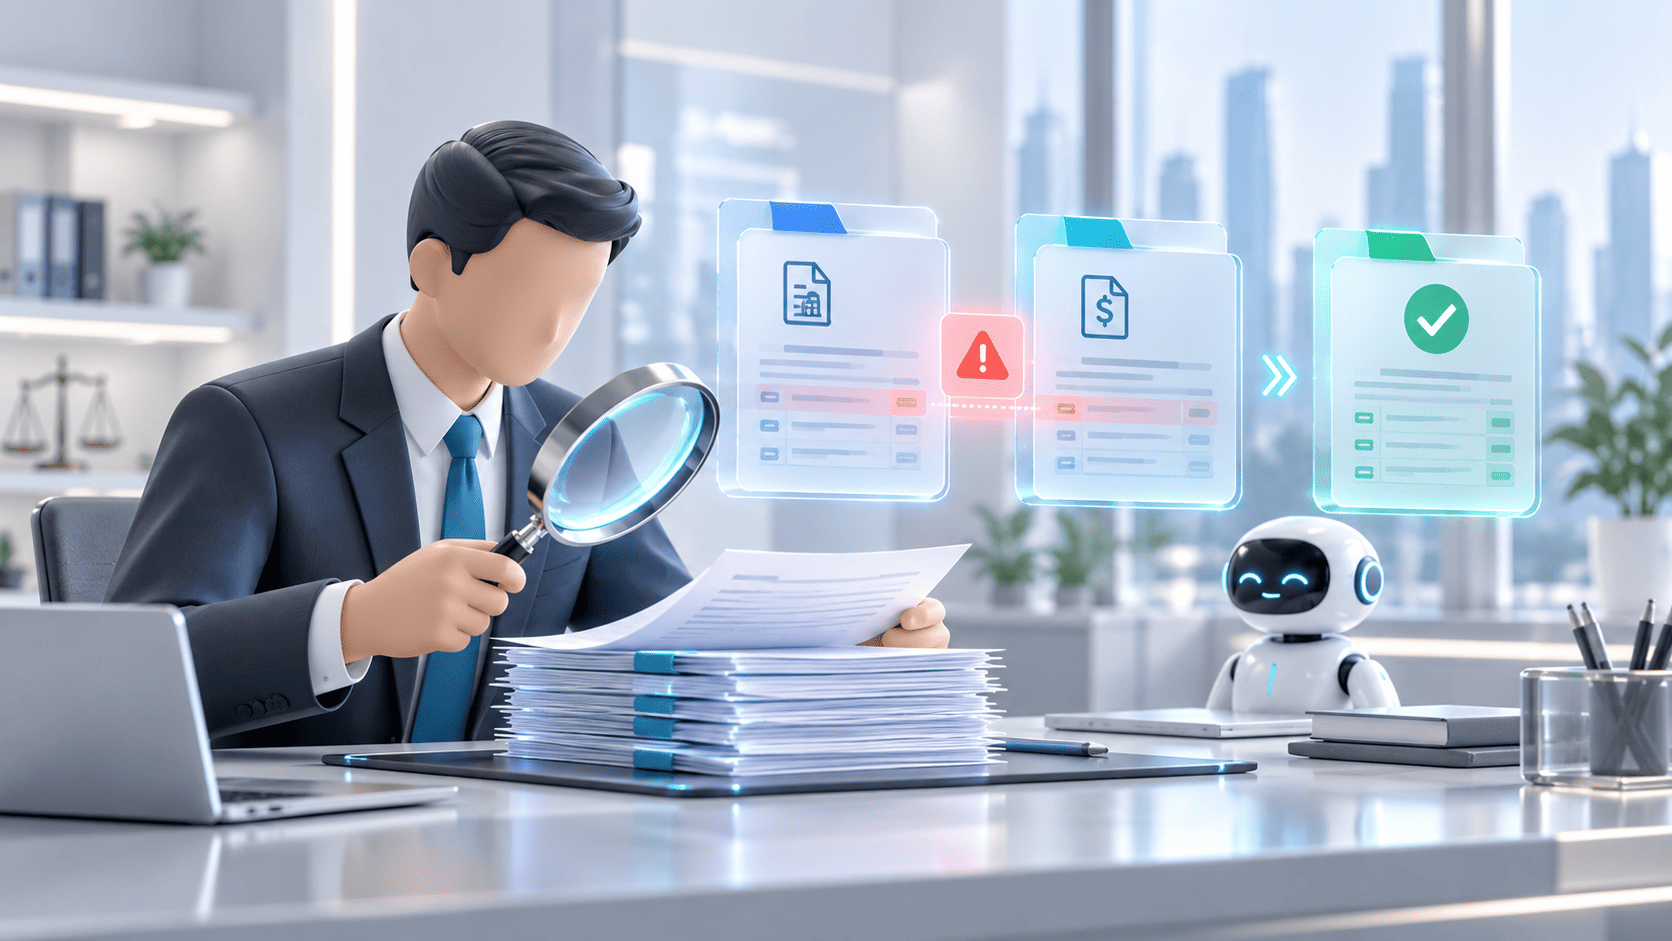
Reconcile in eight steps: six to find the differences, and two to resolve and record them, which is where most of the time goes.
- Obtain the statement for the right supplier and the right period. Where suppliers do not send statements routinely, request them for the suppliers that matter most, starting with those that carry the most spend or the most invoices.
- Validate it. Confirm the supplier on the statement is the one in the vendor master, that the statement date and period match what you are reconciling, and that it is complete, with an opening balance that agrees with the previous statement's closing balance.
- Pull the AP records for the same supplier and period: posted invoices, open items, payments and credits applied.
- Normalize both sides. Put invoice numbers, dates, amounts and currencies into the same format, so that "INV-04438," "4438" and "04438" are recognized as one document.
- Match line by line, starting with exact matches on reference and amount, then looking at near-matches such as the same amount with a slightly different reference.
- Classify every difference: timing, missing on one side, recorded twice, or the wrong amount.
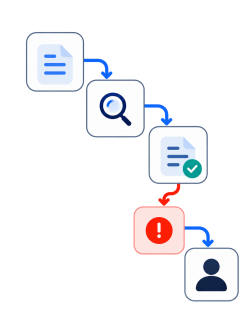
- Investigate and resolve each difference through someone with the authority to decide, using the evidence that difference needs. The resolution matrix later in this article sets out what each kind needs and who decides.
- Document the result: what matched, what differed, what was decided, by whom and when, and which items carry forward to the next reconciliation.
Two habits make the process far more reliable. Match lines, never just closing balances, for reasons the next section's second example shows. And carry every unresolved item forward explicitly, so that next month's reconciliation starts from a known list of open questions and does not rediscover them from scratch.
Vendor Statement Reconciliation Example
Two illustrative cases on supplier accounts show why matching lines matters more than matching totals. The companies and figures are fictional.
When the Balances Differ
The supplier's statement shows a closing balance of $5,300. Accounts payable shows $4,500. The $800 difference needs explaining before anything is posted.
| Item | Supplier statement | AP records | Difference |
|---|---|---|---|
| Invoice 4410 | $2,000 | $2,000 | None |
| Invoice 4425 | $1,500 | $1,500 | None |
| Invoice 4438 | $1,000 | Not recorded | $1,000 |
| Invoice 4451 | $1,000 | $1,000 | None |
| Credit note CR-77 | ($200) | Not recorded | ($200) |
| Closing balance | $5,300 | $4,500 | $800 |
Two items explain the full difference: an invoice the supplier issued that never reached AP, and a credit note the supplier issued that nobody recorded. Neither should be posted on the strength of the statement alone. Invoice 4438 needs the original invoice and, where the client uses them, the purchase order and receiving record, then the normal approval. Credit note CR-77 needs the credit memo itself and approval to record it and decide which invoice it offsets. Until both are resolved, the reconciliation records them as open items with an owner.
When the Totals Agree but the Lines Do Not
The supplier's statement shows $3,000. Accounts payable also shows $3,000. Comparing closing balances, the account looks reconciled.
| Item | Supplier statement | AP records | Difference |
|---|---|---|---|
| Invoice 5101 | $1,500 | $1,500 | None |
| Invoice 5108 | $750 | $750 | None |
| Invoice 5108, entered again | Not on statement | $750 | ($750) |
| Invoice 5114 | $750 | Not recorded | $750 |
| Closing balance | $3,000 | $3,000 | None |
Line by line, AP contains invoice 5108 twice and is missing invoice 5114 entirely. The two errors cancel exactly. A reconciliation that compares totals would pass this account, and the next payment run could pay invoice 5108 twice while invoice 5114 sits unpaid until the supplier chases it or puts the account on hold.
The lesson is the one the step-by-step process builds in: a matching total proves nothing on its own, and matching the lines is the step that finds errors which offset each other.
Why Vendor Statements and AP Records Disagree, and How to Resolve Each Difference
Most differences are timing and clear themselves; the rest are errors on one side, and each kind needs its own evidence and its own decision.
Timing differences come from the gap between when the supplier books something and when you do. A payment sent on the last day of the month appears in your records but not yet on the supplier's statement. An invoice dated before the statement date may not have reached AP yet. These clear by the next statement, and the reconciliation should record them as expected to clear. A timing difference that is still there a month later is no longer timing, and needs investigating.
The genuine differences fall into a small number of kinds, and the matrix below sets out what each needs:
| Difference | Evidence needed | Next action | Who decides |
|---|---|---|---|
| Invoice on the statement, missing from AP | Original invoice; purchase order and receiving record where used | Route through the normal AP approval | The client's approver |
| Payment missing from the statement | Payment confirmation and remittance reference | Ask the supplier to trace and apply it | The client, before any payment is re-sent |
| Credit on the statement, missing from AP | The supplier's credit memo | Record and apply, with approval | The client's approver |
| Possible duplicate invoice | Both documents and the posting history | Hold further payment and investigate | The client's approver |
| Amount mismatch | Contract, invoice, delivery and tax records | Correct the record, or dispute with the supplier | The client, for any correction or dispute |
| Timing difference that does not clear | The prior reconciliation and dated records | Investigate and escalate | The reviewer, then the client |
The evidence column is where reconciliations stall. A difference with no evidence attached sits on a list, gets rediscovered next month, and eventually gets written off or paid without anyone being sure it was right. Gathering the evidence at the moment the difference is found turns a list of discrepancies into a list of decisions.
The last column matters most when someone outside the client does the reconciling, because it decides whether the person who found a difference may also fix it.
Who Can Approve the Fix: Authority and Independence for Accounting Firms
An accounting firm reconciling a client's suppliers can investigate and propose every fix, but for a client it also audits or reviews, the decisions to record, apply, dispute or pay belong to the client, and the reconciliation has to show that they did.
Start with the control that applies to everyone. A supplier statement records the supplier's view of the account. Recording or paying anything on the strength of it still needs the original document and the normal approval route, because statements contain errors too, and because an invoice that appears only on a statement has not been through any of the checks an invoice normally passes.
For firms, the AICPA's Code of Professional Conduct adds a second layer. The AICPA lists reconciliations as a nonattest service, so a firm reconciling for a client it audits or reviews is inside the independence rules for those services:
- Management responsibilities, ET 1.295.030. Authorizing, executing or consummating transactions, or otherwise exercising authority on the client's behalf, is a management responsibility. Performing it for an attest client impairs independence
- Bookkeeping and disbursements, ET 1.295.120. The AICPA's comparison of its Code with government auditing standards lists approving vendor invoices for payment, accepting responsibility to authorize payment of client funds, and signing client checks among the activities that impair independence. Recording transactions the client has approved does not
- General requirements, ET 1.295.040. Before the service starts, the client must agree to take all management responsibilities, designate an individual with suitable skill, knowledge and experience to oversee the service, evaluate its adequacy and results, and accept responsibility for them. The firm must document that understanding in writing, covering the objectives, the services, the client's responsibilities, the firm's responsibilities and any limitations
The AICPA's toolkit adds a caution that fits this work closely. Firms should consider the scope, scale, frequency and duration of a service, because a service that has become part of the client's internal control means the firm has assumed a management responsibility. A monthly reconciliation that a firm runs for years, with the client never looking at it, is exactly that risk. The client has to remain the visible owner of the control: reviewing the results, making the decisions and signing off.
In practice, the reconciliation's own record is the evidence. Each difference shows what the firm found and proposed, which client designee decided, and when.
These rules apply where the firm also performs attest work for the client, such as an audit or review, during the engagement and the period the financial statements cover. For clients the firm does not audit or review, the independence rules do not apply. The same separation is still sound control, and the engagement letter should set out the firm's authority, including whether it may contact suppliers on the client's behalf.
Reconciling Supplier Statements Across Many Clients
Reconciling one company's suppliers is a process; reconciling suppliers for dozens of clients is a service, and the parts that break are the ones a single company never has to think about.
The same supplier, under different IDs. A national supplier might appear in twenty clients' systems under twenty vendor numbers, spelled three different ways. Identifying which statement belongs to which client's vendor record is the first step that fails, and a wrong match there contaminates everything after it.
Statements go to the client's inbox. Suppliers send statements to the address on the account, usually a client mailbox. Collecting them is its own workflow, and it needs an agreement with each client on how statements reach the firm: forwarding rules, a shared mailbox, or direct requests to suppliers.
Contacting suppliers needs authority. Asking a supplier to trace a payment or explain a charge is speaking for the client. The firm needs each client's explicit agreement to do it, in the engagement letter or the written understanding the independence rules require.
Every client has its own calendar and approvers. One client closes on the fifth working day with the controller approving adjustments; another closes quarterly with the owner approving everything. A resolution route that works for one fails for the next, so the routing has to be configured for each client separately.
Each client's records should stay in its own systems. Under the AICPA's hosting services interpretation, a firm that takes responsibility for hosting an attest client's data or records impairs its independence, because it has in effect taken over the client's internal control over its information, as the Journal of Accountancy explains. An automation a firm builds for this work should read from and write back to each client's system of record, with the client's approvals recorded there, so the firm never becomes the custodian of the client's books.
Several services to one client add up. The AICPA's cumulative-effect interpretation, ET 1.295.020, asks firms to evaluate multiple nonattest services together. A firm providing bookkeeping, AP and reconciliations to the same attest client should look at them as a whole.
What to Automate in Vendor Statement Reconciliation
Automate the work of finding differences, assist the work of explaining them, and leave the decisions with someone who has the authority to make them.
Good candidates for automation:
- Collecting statements from mailboxes and supplier portals
- Extracting lines from PDFs, spreadsheets and emailed tables
- Normalizing references, dates, amounts and currencies
- Matching lines, exact first and then near-matches
- Classifying differences by kind
Work a tool can assist with:
- Retrieving the evidence each difference needs, such as the original invoice, the remittance record or the credit memo
- Drafting a query to the supplier for the reviewer to approve and send
- Proposing a resolution, with the evidence attached and the reason stated
Decisions that need a person with authority:
- Recording a missing invoice
- Applying a credit
- Disputing a charge with the supplier
- Releasing or holding a payment
For an attest client, each of those is the client's decision.
Two design choices separate a useful automation from a risky one. False automatic matches have to stay visible to the reviewer, because a confident wrong match removes a real difference from the queue. And every decision has to be recorded with its approver and date, which is both the control and, for firms, the evidence that the client made the call.
Several neighboring processes have their own guides: automating accounts payable for the wider cycle, invoice coding for classifying an invoice the reconciliation recovers, and multi-agent systems for the accounting close for orchestrating reconciliations alongside the rest of the close.
How to Measure Whether Vendor Reconciliation Is Improving
The percentage of lines matched automatically is the easiest number to report, and the least useful on its own. These measures show whether reconciliation is working:
| Measure | What it shows |
|---|---|
| Statement coverage | How much of a risk-ranked supplier list was reconciled in the period |
| Unresolved difference value | What remains unexplained, in money |
| Time to resolve | How long differences stay open |
| Repeat difference rate | Whether the same causes keep returning |
| Credits identified and applied | Whether credits the supplier issued are being used |
| False automatic match rate | Whether wrong matches are slipping past review |
| Handling time per statement | Whether manual work is falling |
The repeat difference rate matters most. A difference that recurs points to a cause upstream of the reconciliation, such as invoices arriving at an address AP does not monitor, or payments sent without remittance references the supplier can apply. Reconciliation will find those differences every month indefinitely. Fixing the upstream cause stops them, and the repeat rate shows which causes are worth fixing first.
Coverage deserves the second look. Few firms reconcile every supplier every month, and few need to. A risk-ranked list, starting with the suppliers that carry the most spend, the most invoices or the most past differences, makes coverage a deliberate choice rather than an accident of which statements happened to arrive.
How Codebridge Builds Reconciliation Automations
Codebridge builds business automations. Performing reconciliations, or selling a packaged reconciliation product, sits outside what we offer.
For a firm that wants vendor statement reconciliation automated, that means building the workflow described in this article inside the firm's and its clients' own systems. Statement collection, extraction, matching and classification are automated. The evidence each difference needs is gathered and attached. Each decision is routed to the client's designated approver and recorded with their name and date, so the firm can show its clients made the calls the independence rules reserve for them.
The closest workflow we already describe is AP invoice resolution, which reads invoices, matches them to the ledger, runs bookkeeping checks and routes exceptions for approval. A reconciliation automation follows the same pattern.
Your firm owns the repository, the prompts and the configuration from day one. The closest reference we can offer, labelled for what it is: Knowledge Cloud, built for a Big Four tax and legal practice, runs an expert review queue with an immutable audit log, so a senior practitioner approves each output before the firm acts on it. A knowledge platform rather than an accounting system. What it demonstrates is the review and approval-record pattern.
Our founding team spent more than a decade at KPMG.
If you want to scope one client's reconciliation workflow, book a 20-minute call.
What is vendor statement reconciliation?
Vendor statement reconciliation, also called supplier statement reconciliation, compares a supplier's statement of account with your accounts payable records to find and resolve differences in invoices, payments, credits and balances. It catches invoices that never reached AP, misapplied payments, unused credits and duplicates.
How often should vendor statements be reconciled?
There is no universal rule. A common approach is to reconcile high-spend, high-volume or previously problematic suppliers each month, and others quarterly or at year end. A risk-ranked supplier list makes coverage a deliberate decision rather than depending on which statements happen to arrive.
Why doesn't my vendor statement match accounts payable?
Usually timing: a payment in transit or an invoice not yet received. Genuine differences include invoices missing from AP, payments the supplier has not applied, unrecorded credits, duplicate entries and amount mismatches. Even matching totals can hide offsetting errors, so compare line by line.
Can I record an invoice from a vendor statement?
Not on the statement alone. An invoice that appears only on a statement needs the original invoice and, where used, the purchase order and receiving record, then the normal approval. Statements contain errors too, and the invoice has not been through any of the usual checks.
Can an accounting firm approve vendor invoices for an audit client?
No. Under the AICPA's independence rules, approving vendor invoices for payment and authorizing payment of client funds impair independence for an attest client. The firm can reconcile, investigate and propose, and the client's designated individual must make and record the decisions.
What should a firm agree with a client before reconciling its suppliers?
For an attest client, the AICPA requires a written understanding before the service starts: the client assumes management responsibilities, names a qualified overseer, evaluates and accepts the results. Firms should also agree how statements reach them and whether they may contact suppliers on the client's behalf.
Can vendor statement reconciliation be automated?
Largely. Collecting statements, extracting lines, normalizing, matching and classifying differences can be automated, and evidence retrieval and supplier queries can be assisted. Recording invoices, applying credits, disputing charges and releasing payments need a person with authority, and for an attest client that person is the client.





Heading 1
Heading 2
Heading 3
Heading 4
Heading 5
Heading 6
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Block quote
Ordered list
- Item 1
- Item 2
- Item 3
Unordered list
- Item A
- Item B
- Item C
Bold text
Emphasis
Superscript
Subscript