AI Answer Summary
An audit documentation checklist is a review tool that confirms each workpaper shows what was done, the evidence, the results and the conclusion before it goes to review or the audit file is closed. Under ISA 230, a checklist is not needed as evidence of compliance where the file already shows it, so its value lies in catching gaps while they are still cheap to fix.
The 25 checks below fall into three stages: the preparer's self-check, the reviewer's check, and file completion. Each one cites its paragraph in PCAOB AS 1215, AICPA AU-C 230 and ISA 230.
Each check is marked Pass, Gap, N/A or Requires judgment. A workpaper with any open Gap or Requires judgment item is not ready for sign-off, whatever share of the checks has passed.
What an Audit Documentation Checklist Is For
An audit documentation checklist is a gate a workpaper passes before it reaches its reviewer, and again before the audit file is closed. The preparer uses it to find gaps before anyone else does; the reviewer uses it to confirm nothing was missed.
It helps to be clear about what a checklist is not for. ISA 230, paragraph A7, says it is unnecessary to document compliance separately, "as in a checklist," where the documents in the audit file already demonstrate it. The workpapers are the evidence. A signed checklist sitting next to a workpaper that does not show its population or its review proves nothing a reviewer or inspector will accept.
The reason to use one anyway is timing. ISA 230, paragraph A1, notes that documentation prepared after the work is done is likely to be less accurate than documentation prepared at the time. A gap the preparer finds before review takes minutes to fix. The same gap found after the file is assembled may be impossible to fix properly, because additions after that point have to be dated, attributed and explained, and missing work cannot be supported by explanation alone.
This checklist covers external financial statement audits. The question of which documents a client should gather for its auditors belongs to the PBC list, and what workpapers are, and how the three standards compare, is covered in our guide to audit workpapers.
How to Use an Audit Documentation Checklist: Three Stages, Four Statuses
Use the checks in three stages, and give every check one of four statuses.
The stages follow the people who handle a workpaper:
- The preparer's self-check, 13 checks, completed before the workpaper is handed on
- The reviewer's check, 8 checks, completed at manager or partner review
- File completion, 4 checks, completed before the report release date and during assembly of the final file
The rule that matters most is simple. A workpaper with any open Gap or Requires judgment item is not ready, whatever share of the checks show Pass. The downloadable template counts open items and deliberately shows no percentage score, because a score of 92% can hide the one item that decides whether the conclusion stands.
The N/A definition matters too. Under ISA 230, a requirement is not relevant only in those two narrow cases, so N/A is a statement about the engagement, with a reason recorded, and never a way to close an awkward check.
The 25-Point Audit Documentation Checklist
Each check below shows its paragraph in each standard, or "None" where a standard has no equivalent, and its type:
- Rule: a tool can confirm it
- Assisted: a tool can flag it, and a person confirms
- Judgment: an auditor decides
Adapt the checks to your firm's methodology and review them with your quality team before use.
Stage 1: The Preparer's Audit Workpaper Checklist
The preparer completes these before handing the workpaper to a reviewer.
Stage 2: The Workpaper Review Checklist
The manager or partner completes these at review.
Stage 3: The Audit File Completion Checklist
These are completed before the report release date and during assembly. The assembly window is 14 days after the report release date under AS 1215, no more than 60 days under AU-C 230, and ordinarily no more than 60 days after the date of the auditor's report under ISA 230. Our workpapers guide compares the three in detail.
Notes. For check 17, the AICPA and IAASB address documentation of misstatements in their misstatement standards, AU-C 450 and ISA 450, rather than in the documentation standards. For check 23, ISA 230 counts from the date of the auditor's report, so it has no separate release-date requirement. Check 20 draws on the PCAOB's 2024 release and the IAASB's 2020 support material, covered below. The AU-C 230 references are cited as quoted by a practicing firm; confirm them against the AICPA's text.
Audit Documentation Checklist Example: An Incomplete Workpaper
Our workpapers guide walks through a complete search for unrecorded liabilities, workpaper L-4, at a fictional manufacturer. Here is what that same workpaper might look like before the preparer's self-check, and which check catches each problem.
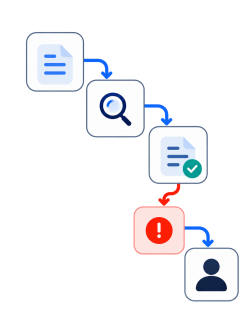
Five of the six problems are caught at stage 1, before a reviewer opens the file. Four of those five come from checks typed Rule or Assisted, so a tool could flag them: the unmatched invoices, the vague procedure, the undisposed exception and the untraceable figure. The fifth, a conclusion that contradicts its own testing schedule, needs an auditor to see that "no exceptions" cannot stand while a $48,200 difference sits unresolved.
The sixth problem, the missing review record, belongs to stage 2, which is exactly where the reviewer should find it.
The completed version of this workpaper, with every check passing, is in our guide to audit workpapers.
Which Audit Documentation Checks a Tool Can Perform
Of the 25 checks, 13 are Rule, 8 are Assisted and 4 are Judgment. A tool can confirm or flag 21 of them, and the 4 that remain belong to auditors.
The standards treat automated work the same way as manual work, and that shapes how these checks apply. In adopting its 2024 amendments on technology-assisted analysis, the PCAOB said the documentation requirements of AS 1215 apply also to procedures involving such analysis. The IAASB's 2020 support material on documentation when using automated tools and techniques says the documentation requirements are the same for manual and automated work, though automated tools can change what needs to be documented.
Two checks follow directly from that. Check 20 requires every figure or test a tool produced to record its source file, version, location, any conversion applied and who approved it. Check 21 confirms that nothing the conclusion relies on rests on an explanation that exists only in someone's head, which matters more when a tool did the work, because nobody can ask a tool later what it meant.
The four Judgment checks stay with auditors: inconsistent information, whether the conclusion matches the results, the significance of findings, and whether the file stands on its own. A tool can surface a conclusion that does not match its testing schedule. Deciding what the conclusion should be is the auditor's call. Our article on how accurate AI needs to be for accounting automation covers how to set review thresholds by task.
Download the Audit Workpaper Checklist Template
The template turns the 25 checks into a working file a team can use on a live engagement:
- Checklist: all 25 checks with their references and types, a status dropdown with the four values, and columns for evidence reference, issue, owner, reviewer decision and date
- Instructions: how to use the stages and statuses, with a worked example row
- Readiness: open Gap and Requires judgment items counted by stage, with no percentage score
- Standards key: what each cited paragraph requires, in one line
Get the audit documentation checklist template as a Google Sheet, and make your own copy (File, then Make a copy) to use on an engagement.
Adapt it to your firm's methodology and review it with your quality team before you rely on it.
Where Codebridge Fits
The 21 Rule and Assisted checks are the ones a workflow can run before a workpaper reaches its reviewer, so reviewers spend their time on the four that need them.
Our WIP and Realization Monitoring workflow can be scoped to audit workpaper preparation ahead of sign-off, as described on our professional services page. Built as a custom pre-review workflow, it runs the Rule checks, flags the Assisted ones with their evidence attached, and routes the Judgment checks to the reviewer. Sign-off stays with the engagement team, and every action the workflow takes is logged. The firm owns the repository, the prompts and the configuration from day one.
The closest reference we can offer, labelled for what it is: Knowledge Cloud, built for a Big Four tax and legal practice, runs an expert review queue with an immutable audit log, so a senior practitioner approves each output before the firm acts on it. A knowledge platform rather than an audit system. What it demonstrates is the review and audit-trail pattern.
Our founding team spent more than a decade at KPMG.
If you want to look at which checks take your reviewers the most time, book a 30-minute call.





Heading 1
Heading 2
Heading 3
Heading 4
Heading 5
Heading 6
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Block quote
Ordered list
- Item 1
- Item 2
- Item 3
Unordered list
- Item A
- Item B
- Item C
Bold text
Emphasis
Superscript
Subscript