The ABA model sets quarterly as the minimum, California and Iowa require monthly, Illinois requires quarterly, and published guides contradict all of them. How often to reconcile, who has to sign, and what a tool can check before a lawyer does.
AI Answer Summary
Three-way reconciliation compares a trust account's adjusted bank balance, the firm's trust account journal, and the total of every individual client ledger. All three must agree, and any gap means client money is unaccounted for.
How often depends on where you practise. The ABA's model rules set quarterly as the minimum and monthly as the preferred practice. California and Iowa require monthly reconciliation, and Illinois requires it at least quarterly. Many published guides say monthly in every state, which the rule texts do not support.
California now requires firms to name a designated licensee for each trust account, responsible for performing or supervising the monthly reconciliation, and naming one does not absolve the firm's other lawyers. A tool can do the matching and flag exceptions before month-end. A named lawyer still reviews the result and signs.
What Is Three-Way Reconciliation for a Law Firm Trust Account?
Three-way reconciliation for a law firm trust account tests that three numbers agree. Any gap between them means client money is unaccounted for.
| Balance | Where it comes from | What a mismatch suggests |
|---|---|---|
| Adjusted bank balance | The bank statement, plus deposits in transit, minus outstanding checks | A missing or miskeyed bank entry |
| Trust account journal | The firm's running record of every deposit and disbursement | An unrecorded or double-recorded transaction |
| Sum of client ledgers | The total across every client's individual ledger | A transaction posted to the wrong client, or a client balance running negative |
The mechanics will be familiar to anyone who has run a month-end bank reconciliation, and our guide to automating reconciliation covers the general process. What makes trust accounting different is whose money it is. The balance belongs to clients and third parties, so a mismatch is a professional-conduct problem as well as a bookkeeping one, and the rules on how often to check, who checks, and what gets kept are set by courts and bar regulators rather than by the firm's finance team.
That last point is where most of the published guidance goes wrong.
How Often Must a Law Firm Reconcile Its Trust Account?
It depends on the jurisdiction, and the four verified below give two different answers.
| Jurisdiction | Reconciliation requirement | Record retention | Source |
|---|---|---|---|
| ABA Model Rules for Client Trust Account Records | Quarterly minimum, monthly preferred | Five years, bracketed in the model | Model Rule 1(i) and comment |
| California | Monthly, written, three-way | Five years | Rule 1.15(d)(3) and (e) |
| Iowa | Monthly "triple reconciliation" | Six years | Iowa Court Rule 45.2(3) |
| Illinois | At least quarterly, three-way | Check the rule | Rule 1.15A(b)(7) |
| Other states | Check your own rule | Check your own rule | Not verified here |
ABA Model Rules: Quarterly Minimum, Monthly Preferred
The ABA's Model Rules for Client Trust Account Records require copies of monthly trial balances and quarterly reconciliations, with both intervals in brackets for each jurisdiction to adopt or adjust. The comment is plain about the trade-off: quarterly is recommended only as a minimum, and monthly is the preferred practice, because an error is far harder to find among three months of transactions than among one.
California: Monthly Written Three-Way Reconciliation
California requires more. As the State Bar's Handbook on Client Trust Accounting explains, Rule 1.15(d)(3) and (e) require a monthly reconciliation balancing the client ledgers, the account journal and the bank statement, recorded in writing and kept for five years. The State Bar also publishes a Monthly Reconciliation Supervisory Review form for lawyers who have someone else do the work, which is itself a signal of who the State Bar expects to be accountable.
Illinois: Quarterly Three-Way Reconciliation Under Rule 1.15A
Illinois reorganised its trust account rules on 1 July 2023. Rule 1.15A(b)(7) now requires lawyers to prepare and maintain three-way reconciliation reports on at least a quarterly basis, and paragraph (c) sets out the method step by step. Quarterly is the floor, and nothing in the rule prevents a firm from reconciling more often.
Why Published Trust Account Guides Contradict Each Other
Search for how often to reconcile a trust account and the first page of results will tell you monthly in every state. The rule texts above say otherwise. One vendor's guide to Illinois states that the rule requires monthly reconciliation and specifically not quarterly, which is the reverse of what Rule 1.15A says. Iowa, meanwhile, does require monthly "triple reconciliations" and keeps the records for six years.
The likely cause is understandable. Monthly is the safer standard, the ABA prefers it, and several states require it, so writers flatten a sensible recommendation into a universal rule. The practical answer survives the confusion: reconcile monthly wherever you practise, and read your own state's rule for the minimum and the retention period, because those are what a regulator will measure you against.
Who Is Responsible for Trust Account Reconciliation? California's Designated Licensee
The lawyer responsible for the account is responsible for the reconciliation, and California has turned that into a named role reported to the regulator.
The State Bar's rules for its Client Trust Account Protection Program, the program created after the Girardi scandal, now require each firm to name a designated licensee for every trust account. Under Rule 2.5:
- The designated licensee is the primary account holder or signatory on the account
- They are responsible for performing or supervising the monthly reconciliation, and for answering other lawyers' questions about the account
- From 1 January 2026, annual registration must give their name and license number, and the bank must be served a notice identifying them
- Being named does not absolve any other lawyer in the firm of their own duties
That wording answers the question most firms ask, which is whether a bookkeeper or outside accountant can take this off a lawyer's hands. "Performing or supervising" lets someone else do the matching and leaves the responsibility where it was. A Daily Journal analysis described compliance as a non-delegable duty that survives hiring accounting professionals or training staff, and the rule text supports that reading.
There is firm-level exposure too. Under Rule 2.6, if a lawyer is found noncompliant during a review, any attorney with supervising or managerial responsibility over them can also be found noncompliant.
All of this is California. Other states do not have the designated licensee role, though most apply their supervision rules to non-lawyer staff who handle client money, and the role is a sensible structure for any firm to copy.
Do Trust Accounting Platforms Already Reconcile Automatically? What They Miss
Often, yes, at least for the arithmetic. An American Bar Association Law Practice Today article from May 2025 notes that specialist platforms can automate three-way reconciliation, and many practice management systems compare the three balances for you.
What a platform cannot fix is what it is given. Each of these produces a reconciliation where the arithmetic is right and the underlying entries are wrong:
- A check written and never recorded in the ledger
- A deposit arriving with no client attached, so it sits unidentified
- A disbursement made before the client's funds cleared, which can draw on another client's money
- A client ledger running negative
- An operating expense paid from trust, or an earned fee left in trust after it should have moved
- A stale check that never clears and sits as a permanent reconciling item
None of these is exotic. They come from ordinary volume: busy months, a settlement that lands while the paralegal is on leave, a wire that arrives with a reference nobody recognises.
The ABA's own reasoning for preferring monthly reconciliation applies here with more force. If an error is easier to find in one month than in three, it is easier still to find on the day it happens. A check that runs continuously against the bank feed catches most of the items above while they are still small and still explainable.
What Automated Trust Account Reconciliation Can Flag, and What a Lawyer Must Decide
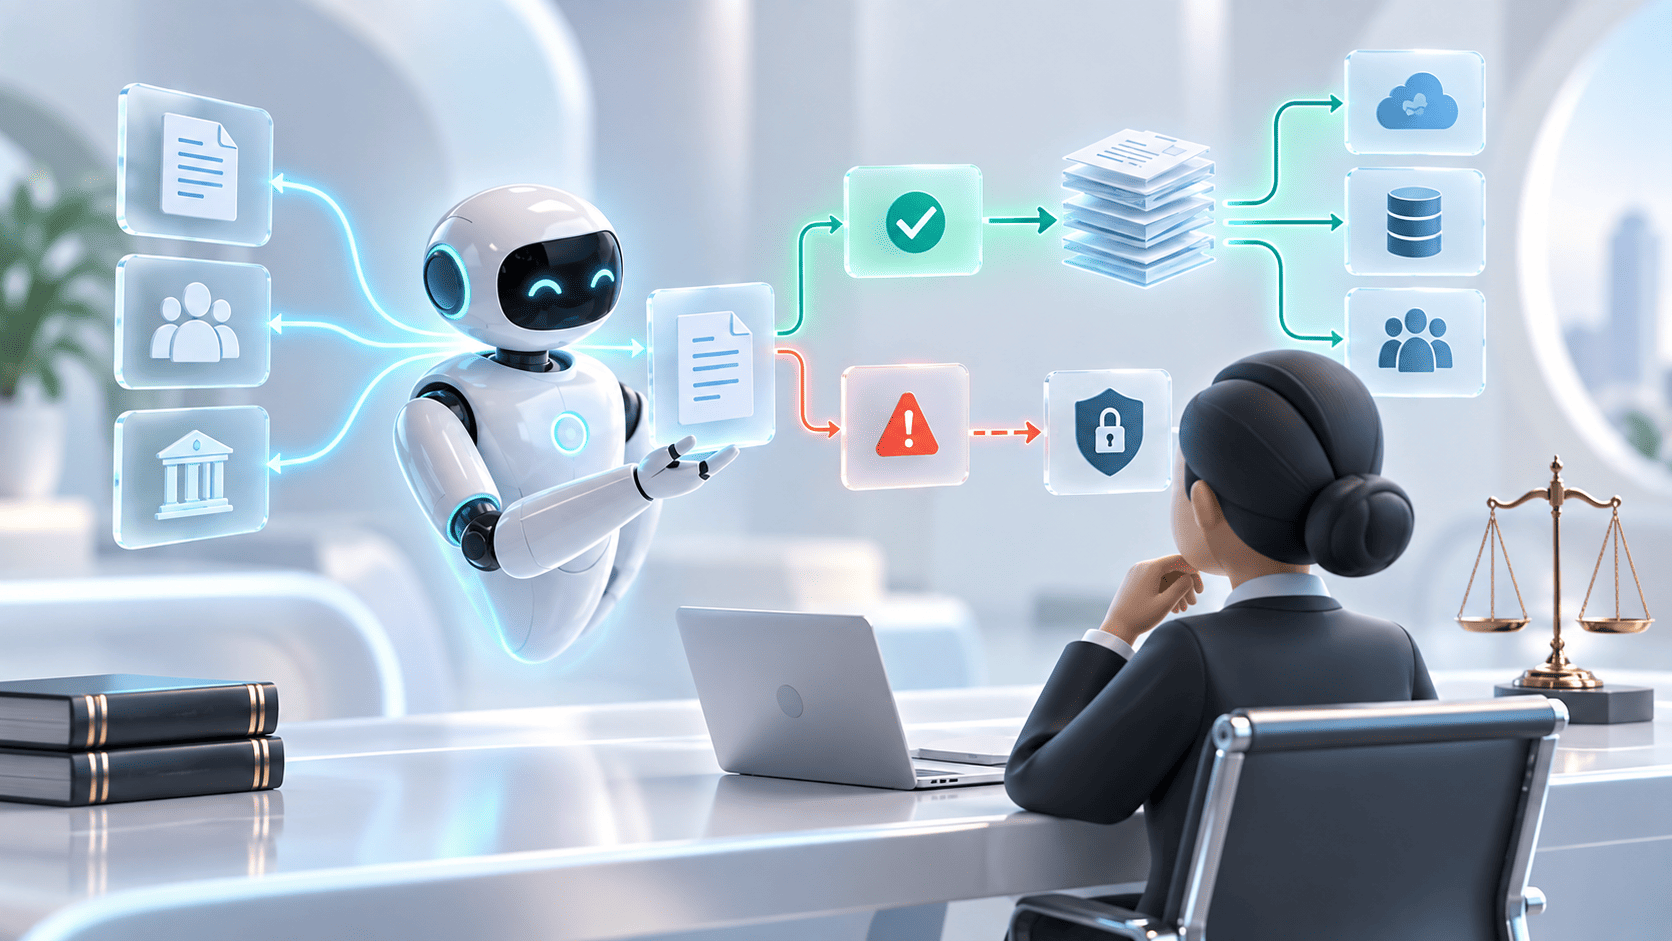
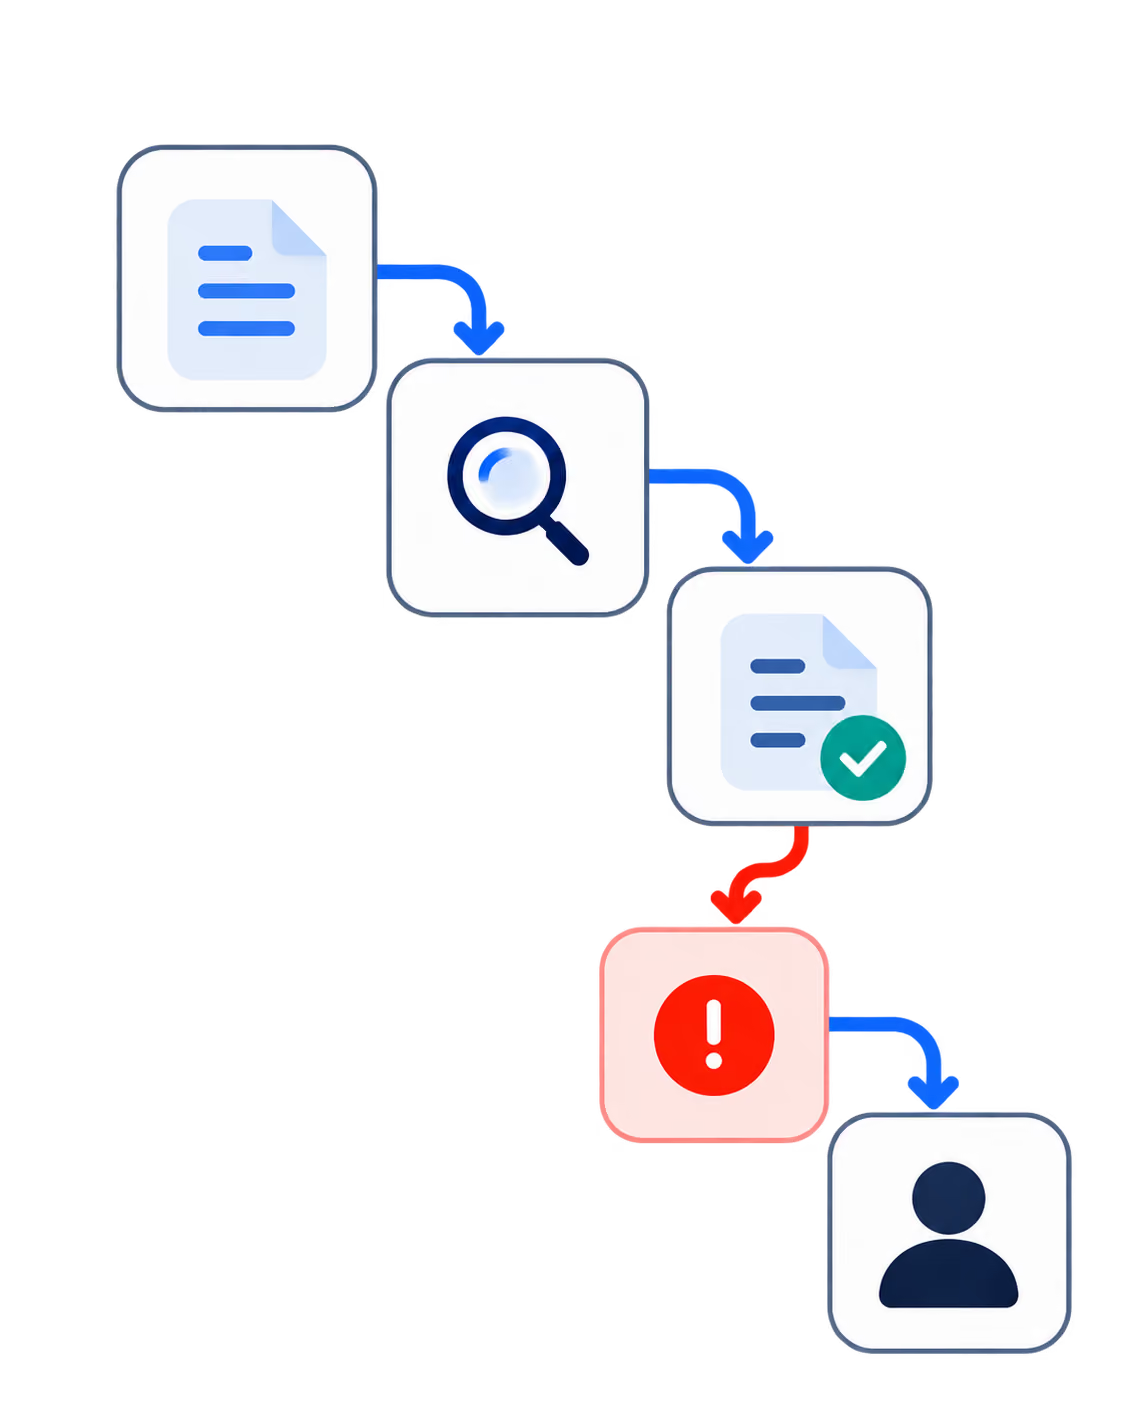
A tool can flag exceptions and prepare the reconciliation workpaper. The designated lawyer decides what each exception means and signs.
| Check | What it catches | Who decides |
|---|---|---|
| Negative client balance | A disbursement exceeding a client's funds | The responsible lawyer |
| Unidentified deposit | Money received with no client matched | The responsible lawyer |
| Unrecorded or stale item | A bank line with no ledger entry, or a check outstanding too long | The bookkeeper, reviewed by the signer |
| Operating payment from trust | A commingling risk | The responsible lawyer |
| Funds held past a deadline | Money sitting after it should have been distributed | The responsible lawyer |
| Three-way mismatch | The three balances disagree | The designated lawyer, before sign-off |
The division is deliberate. Most of what sits in the right-hand column is a judgement about a client's money, and the rules put those judgements on a lawyer. What a tool changes is when the lawyer sees the problem: during the month, with the context still fresh, instead of after month-end when someone has to reconstruct what happened.
Two cautions. This table is our view of where checking helps, and we know of no study that measures how much automation reduces trust accounting errors, so we have not quoted any vendor's claims. And because client ledgers hold confidential financial information, any tool that touches them falls under the same rules as every other AI system in the firm. Our article on law firm AI policy covers which tools are approved and what data each may see.
Trust Accounts When a Lawyer Leaves or Two Firms Merge
When a lawyer leaves or firms combine, responsibility for the trust account changes hands, and the rules put short clocks on it.
California's Rule 2.5 is specific. From 1 January 2026, if the designated licensee goes inactive, becomes ineligible to practise, or stops practising with the firm, the firm has 30 days to close the account or name a new designated licensee and serve a fresh notice on the bank. A departure that nobody connects to the trust account becomes a compliance failure a month later.
The ABA model addresses the other end. Rule 4 requires the partners of a dissolving firm to make reasonable arrangements for keeping its trust account records, and Rule 5 puts the same duty on the seller of a practice. State adoptions such as South Carolina's add in the comment that each partner may be held responsible for keeping those records available, whatever the partners agree among themselves.
A merger raises one more problem, the same one that breaks conflicts checks. Two firms bring two sets of client ledgers built to different conventions, and the same client can appear under different names in each. Our article on lateral hire conflict checks covers why name matching fails when databases combine. For trust accounts, the consequence is a combined ledger that reconciles in total and misallocates between clients.
What to Record to Prove a Trust Account Reconciliation Was Done
The reconciliation that counts is the one you can produce when someone asks for it.
California shows what asking looks like. Under Rule 2.6, a firm selected for a compliance review has 30 days from the notice to name a State Bar-approved CPA, who performs the review at the firm's expense, and to provide the records requested. The review covers at least one year of trust account activity. If it leads to an investigative audit, that covers at least three years, with records due within 14 days of the notice.
What to keep, so that request is routine:
- The written reconciliation for each period, signed and dated by the responsible lawyer
- The supervisory review, where someone other than that lawyer did the work
- A log of every exception found, who resolved it, how and when
- The bank statements, account journal and client ledgers behind each reconciliation
- All of it for the retention period, which is five years under the ABA model and in California, six in Iowa, and varies elsewhere
The scale explains why California built this. The State Bar's 2023 Annual Report found more than 103,000 California attorneys safeguarding an estimated $11 billion to $14 billion across more than 59,000 client trust accounts. Nearly one-fourth of all complaints processed in the investigation stage that year concerned how lawyers handled client money in those accounts. That is one state, in one year, shortly after a program that increased reporting, so it is not a national figure. It is still a clear signal of where a regulator looks first.
How Codebridge Works with Law Firms on Trust Account Reconciliation
We build the checking layer around the trust ledger a firm already keeps. The data stays in the firm's system of record. Exceptions from the table above go to the designated lawyer during the month, the reconciliation workpaper is prepared for their review, and the approval is recorded so the firm can produce it when a compliance review arrives.
We do not hold client funds, we are not your accountants, and we do not sign reconciliations. Those stay with your lawyers and your finance team.
One workflow goes live in three weeks, wired into the systems the firm already runs, and your firm owns the repository, the prompts and the configuration from day one.
The closest reference we can offer, labelled for what it is: Knowledge Cloud, built for a Big Four tax and legal practice, runs an expert review queue with an immutable audit log, so a senior practitioner approves each output before the firm acts on it. A research platform rather than a trust accounting system. What it demonstrates is the review and audit pattern.
Our founding team spent more than a decade at KPMG.
If you want to look at what your trust account checks catch today, book a 20-minute call.
How often must a law firm reconcile its trust account?
It depends on the jurisdiction. The ABA's model rules set quarterly as the minimum and monthly as the preferred practice. California and Iowa require monthly reconciliation, and Illinois requires it at least quarterly. Reconciling monthly is the safer standard everywhere, and your own state's rule sets the minimum.
Is three-way reconciliation required for a law firm trust account?
In many jurisdictions, yes, by name or in substance. It compares the adjusted bank balance, the trust account journal and the sum of all client ledgers, which must agree. California requires a written monthly three-way reconciliation, and Illinois requires three-way reconciliation reports at least quarterly.
Can a bookkeeper or outside accountant do the trust account reconciliation?
They can do the work, but the lawyer stays responsible. California's rules make the designated licensee responsible for performing or supervising the monthly reconciliation, and naming one does not absolve other lawyers in the firm. Hiring accounting help does not transfer the lawyer's duty.
What is a designated licensee in California?
The lawyer a firm names for each trust account under the State Bar's Client Trust Account Protection Program. They are the primary account holder or signatory and are responsible for performing or supervising the monthly reconciliation. From 1 January 2026, their name and license number must be reported to the State Bar.
Can law firm trust accounting be automated?
The arithmetic largely can, and many platforms already compare the three balances. A tool can also flag exceptions such as negative client balances or unidentified deposits during the month. Deciding what each exception means, and signing the reconciliation, stays with the responsible lawyer.
What should a firm do if its trust account does not reconcile?
Review the records for entries that do not match, and for addition or subtraction errors, until all three figures agree, as Illinois' rule commentary describes. Common causes include unrecorded checks, unidentified deposits and transactions posted to the wrong client. Resolve and document each item before signing.





Heading 1
Heading 2
Heading 3
Heading 4
Heading 5
Heading 6
Lorem ipsum dolor sit amet, consectetur adipiscing elit, sed do eiusmod tempor incididunt ut labore et dolore magna aliqua. Ut enim ad minim veniam, quis nostrud exercitation ullamco laboris nisi ut aliquip ex ea commodo consequat. Duis aute irure dolor in reprehenderit in voluptate velit esse cillum dolore eu fugiat nulla pariatur.
Block quote
Ordered list
- Item 1
- Item 2
- Item 3
Unordered list
- Item A
- Item B
- Item C
Bold text
Emphasis
Superscript
Subscript